
Florida · 6.2M owner-occupied homes
The highest insurance burden in America has an address.
The storm passes
Above the clouds, it’s weather. Below them, it’s a bill.
OIR-B1-1802 · Rev. 04/26
Seven features. One state form. Thousands back.
Your storm bill, decoded.
Your storm bill, decoded.
An instant storm-resilience & insurance-savings dossier for Florida homeowners. Address in, twelve-page money dossier out.
Report in two minutes. Savings for years. AI-generated media.
Scroll — the descent
AI-generated media. The emotional register is relief — light breaking through, money saved.
The context · cited, not scary
Miami pays $22,718 a year. Some of that is optional.
Florida homeowners carry the highest insurance burden in America. Typical HO-3 premiums run $6,645 in Tampa, $8,649 in Cape Coral, and $22,718 in the Miami metro — 3.7% of home value (Realtor.com 2025 via Insurify).
Verified wind-mitigation features cut the windstorm portion 25–45% — worth $400–$3,600 a year in real savings for fully mitigated homes.
Yet the only ways to learn your number are a $75–150 inspector visit — or free climate scores that got pulled from listings after a seller sued over a $100,000 loss. Nobody sells homeowners the money version. We do.
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
The storm tape · OIR-B1-1802 (Rev. 04/26)
Seven features. Every dollar they’re worth.
The state scores your home on these seven features. Most homeowners can name two. The tape shows all seven — with the money attached.
Shingle / tile / metal field, fastening schedule at eaves
Roof covering
What your roof is covered with — and whether it meets the Florida Building Code era your discount depends on.
Modeled annual value if documented
$120–$480/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Plywood-to-truss nailing pattern, 8d ring-shank spacing
Roof deck attachment
How the plywood skin is nailed to the trusses. The strongest pattern is invisible from the street — and worth real money.
Modeled annual value if documented
$150–$620/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Hurricane strap detail — truss to top plate, single-wrap
Roof-to-wall connection
The steel straps that keep your roof married to your walls. The single highest-ROI feature on most pre-2002 homes.
Modeled annual value if documented
$200–$850/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Hip vs. gable — plan view of a Florida ranch
Roof geometry
Hip roofs deflect wind; gables catch it. Your geometry was set the day the trusses went up — the form just prices it.
Modeled annual value if documented
$180–$740/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Peel-and-stick membrane underlayment at valleys
Secondary water resistance
A sealed underlayment that keeps water out even if shingles leave. Quiet, cheap, and almost never documented.
Modeled annual value if documented
$80–$320/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Impact-glass section + shutter track detail
Opening protection
Windows, doors, skylights: impact glass or rated shutters on every opening. The feature homeowners feel — and carriers pay for.
Modeled annual value if documented
$250–$1,100/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Braced garage door elevation, wind-load rating plate
Garage door
The largest opening in the house — and the most common point of failure. A rated door or brace kit closes the loop.
Modeled annual value if documented
$60–$260/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
My Safe Florida Home · FY2025–26
The state's money
Florida appropriated $280M for hardening: free wind-mitigation inspections and matching grants up to $10,000 for eligible homeowners.
Every dossier includes the eligibility check and the application steps — the grant navigator is why the roadmap has a funding column.
My Safe Florida Home is a program of the State of Florida. Stormbill is not affiliated with the State of Florida; program rules change — verify current eligibility at mysafeflhome.com.
AI-generated media. All savings bands are illustrative estimates — confirm with your licensed agent.
The scale of the sky
The storm is the backdrop. The savings are the story.
AI-generated media.
The money page · dossier §3 of 6
This is the page that pays for itself.
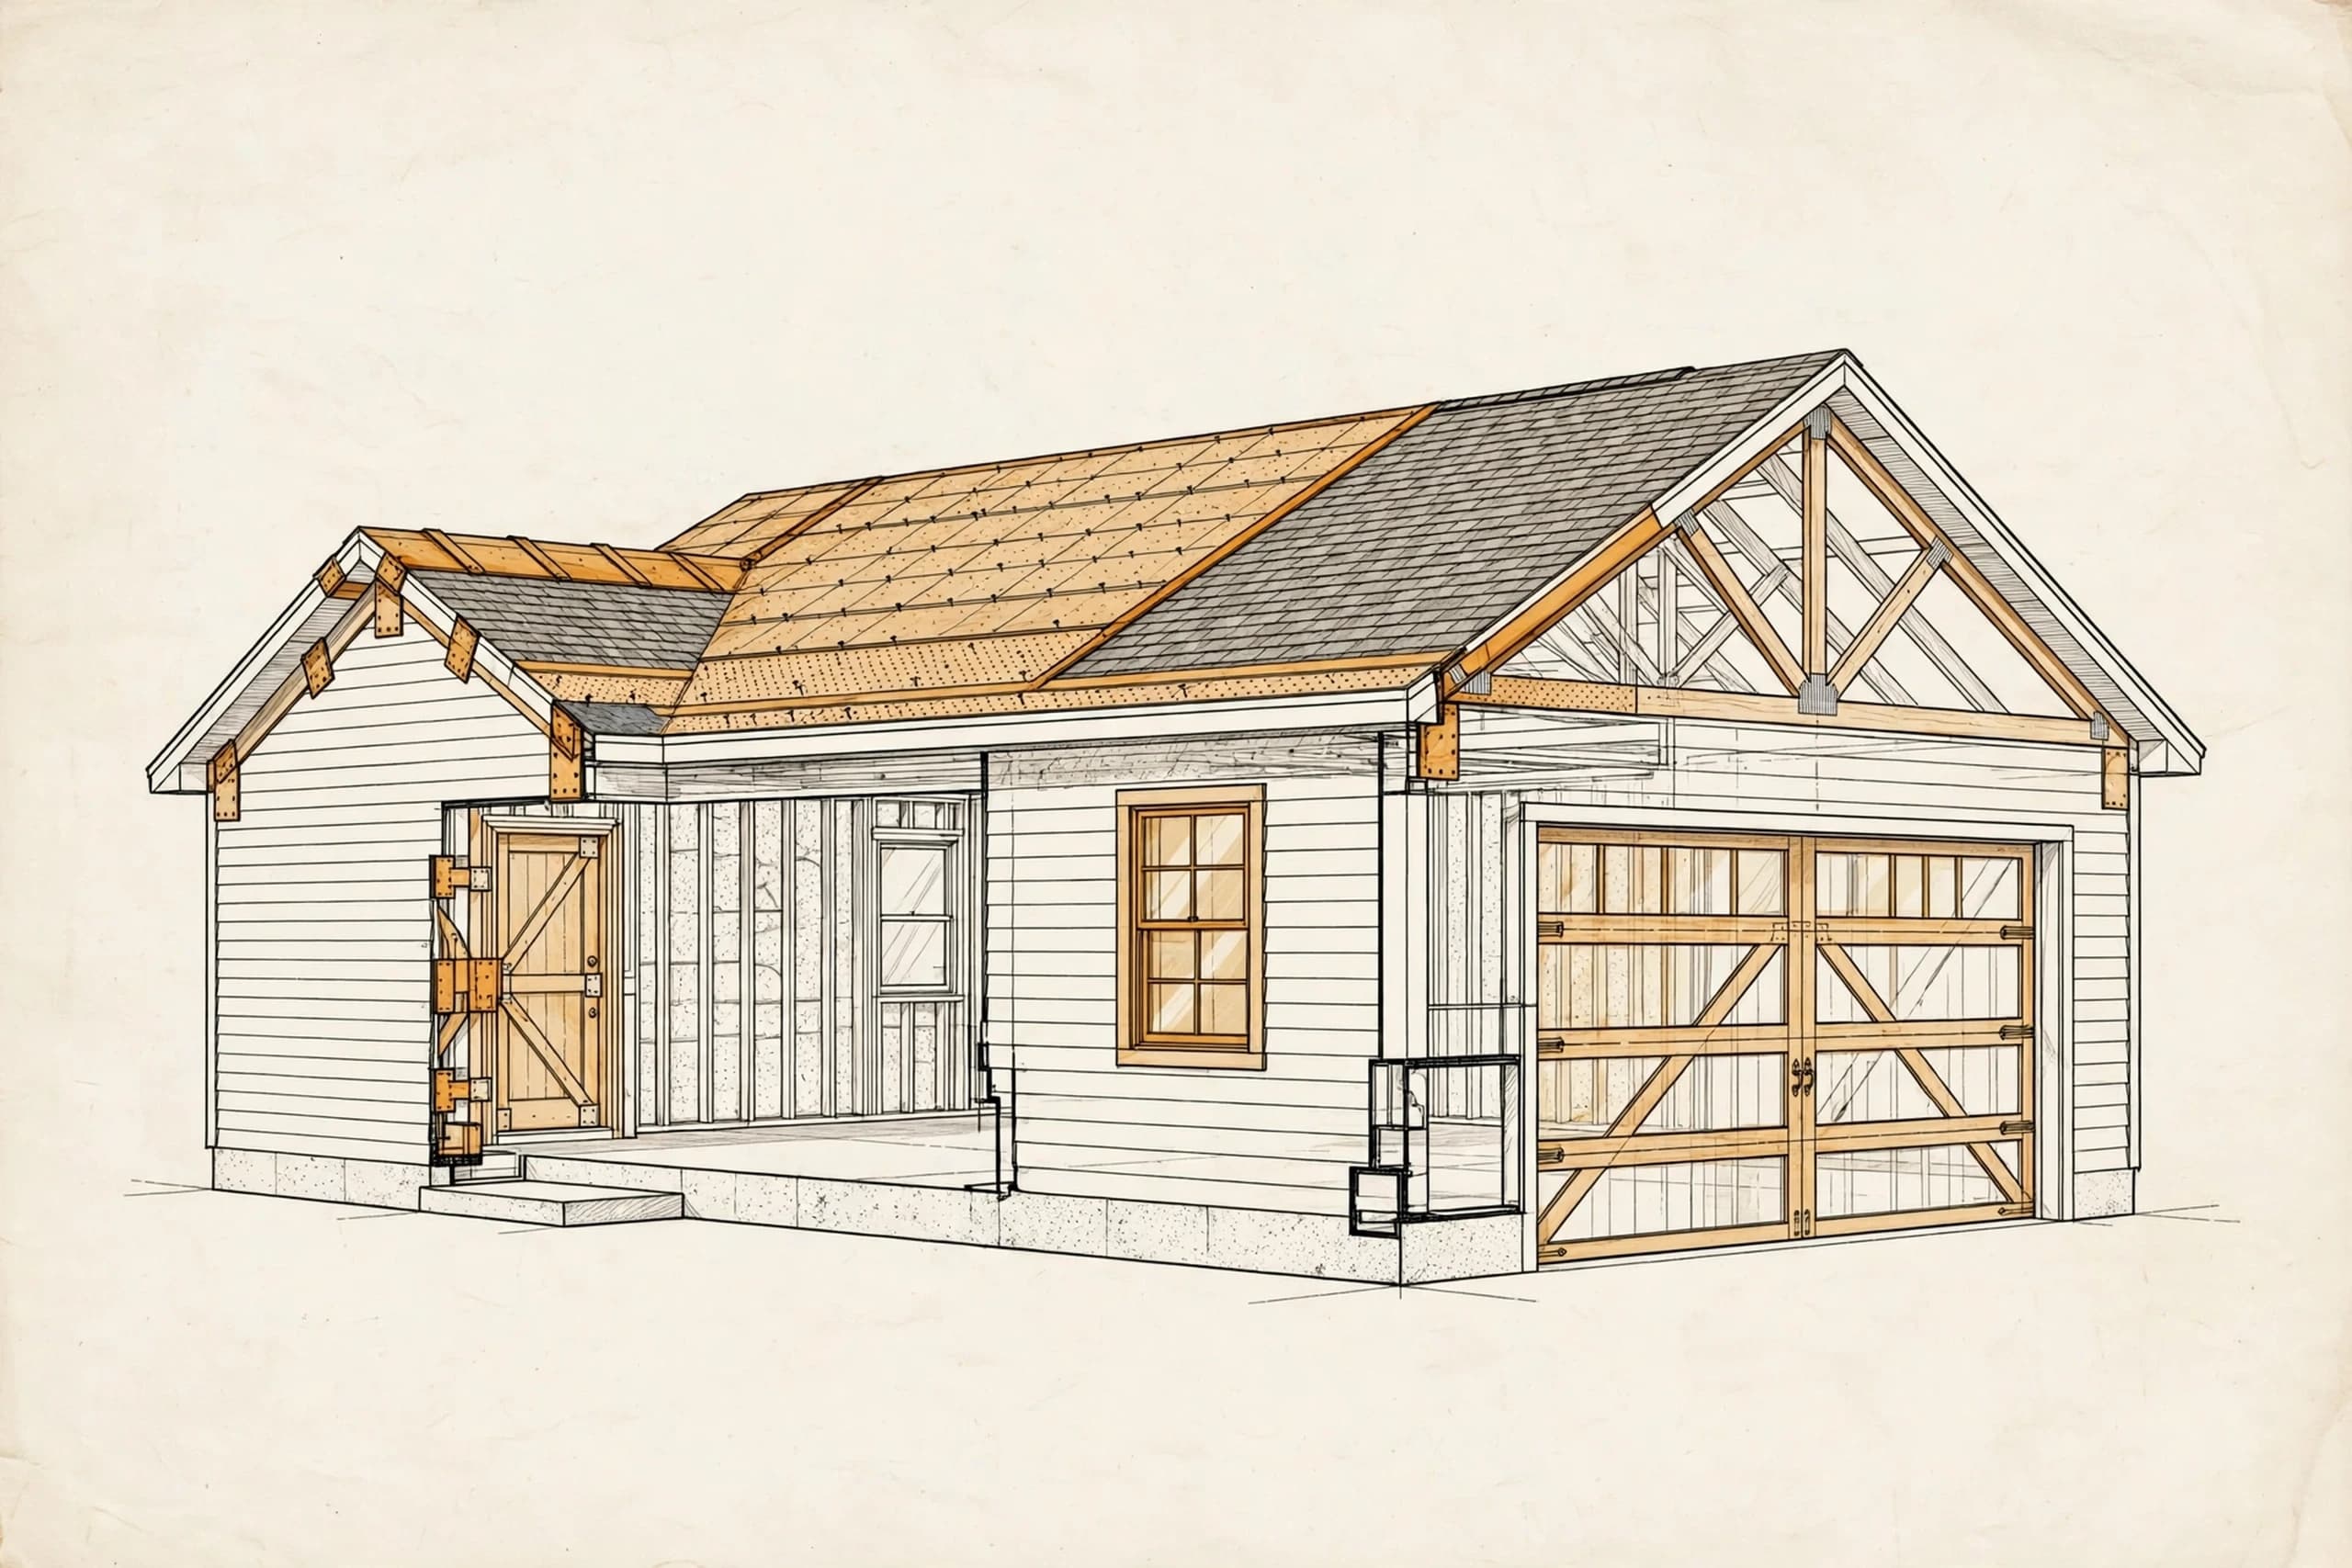
AI-generated media. Blueprint cutaway is illustrative of a typical gable roof.
Modeled annual savings · illustrative
$0/yr
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Five features this demo home likely lacks. Each one has a state-published credit waiting — the dossier turns “likely missing” into a ranked upgrade plan with payback math.
The craft · trust through data
Built from public records, not scare data.
Every figure in the dossier traces to a cited source. When the state changes the form — as it did in April 2026, the first overhaul in over a decade — the scoring engine updates in days, not inspection seasons.
- County property appraisersBuild year, construction type, permit history
- FEMA Flood Map Service CenterFlood zone, base flood elevation
- FL wind-borne debris mapsASCE 7-22 wind-speed regions
- OIR-B1-1802 (Rev. 04/26)The state's own scoring logic, versioned in code
- My Safe Florida Home rulesGrant eligibility, published program mechanics
- Your eight answersThe features no public dataset has
Methodology score, not a carrier rating. Built from public records, not scare data. Not insurance advice — confirm with your licensed agent.
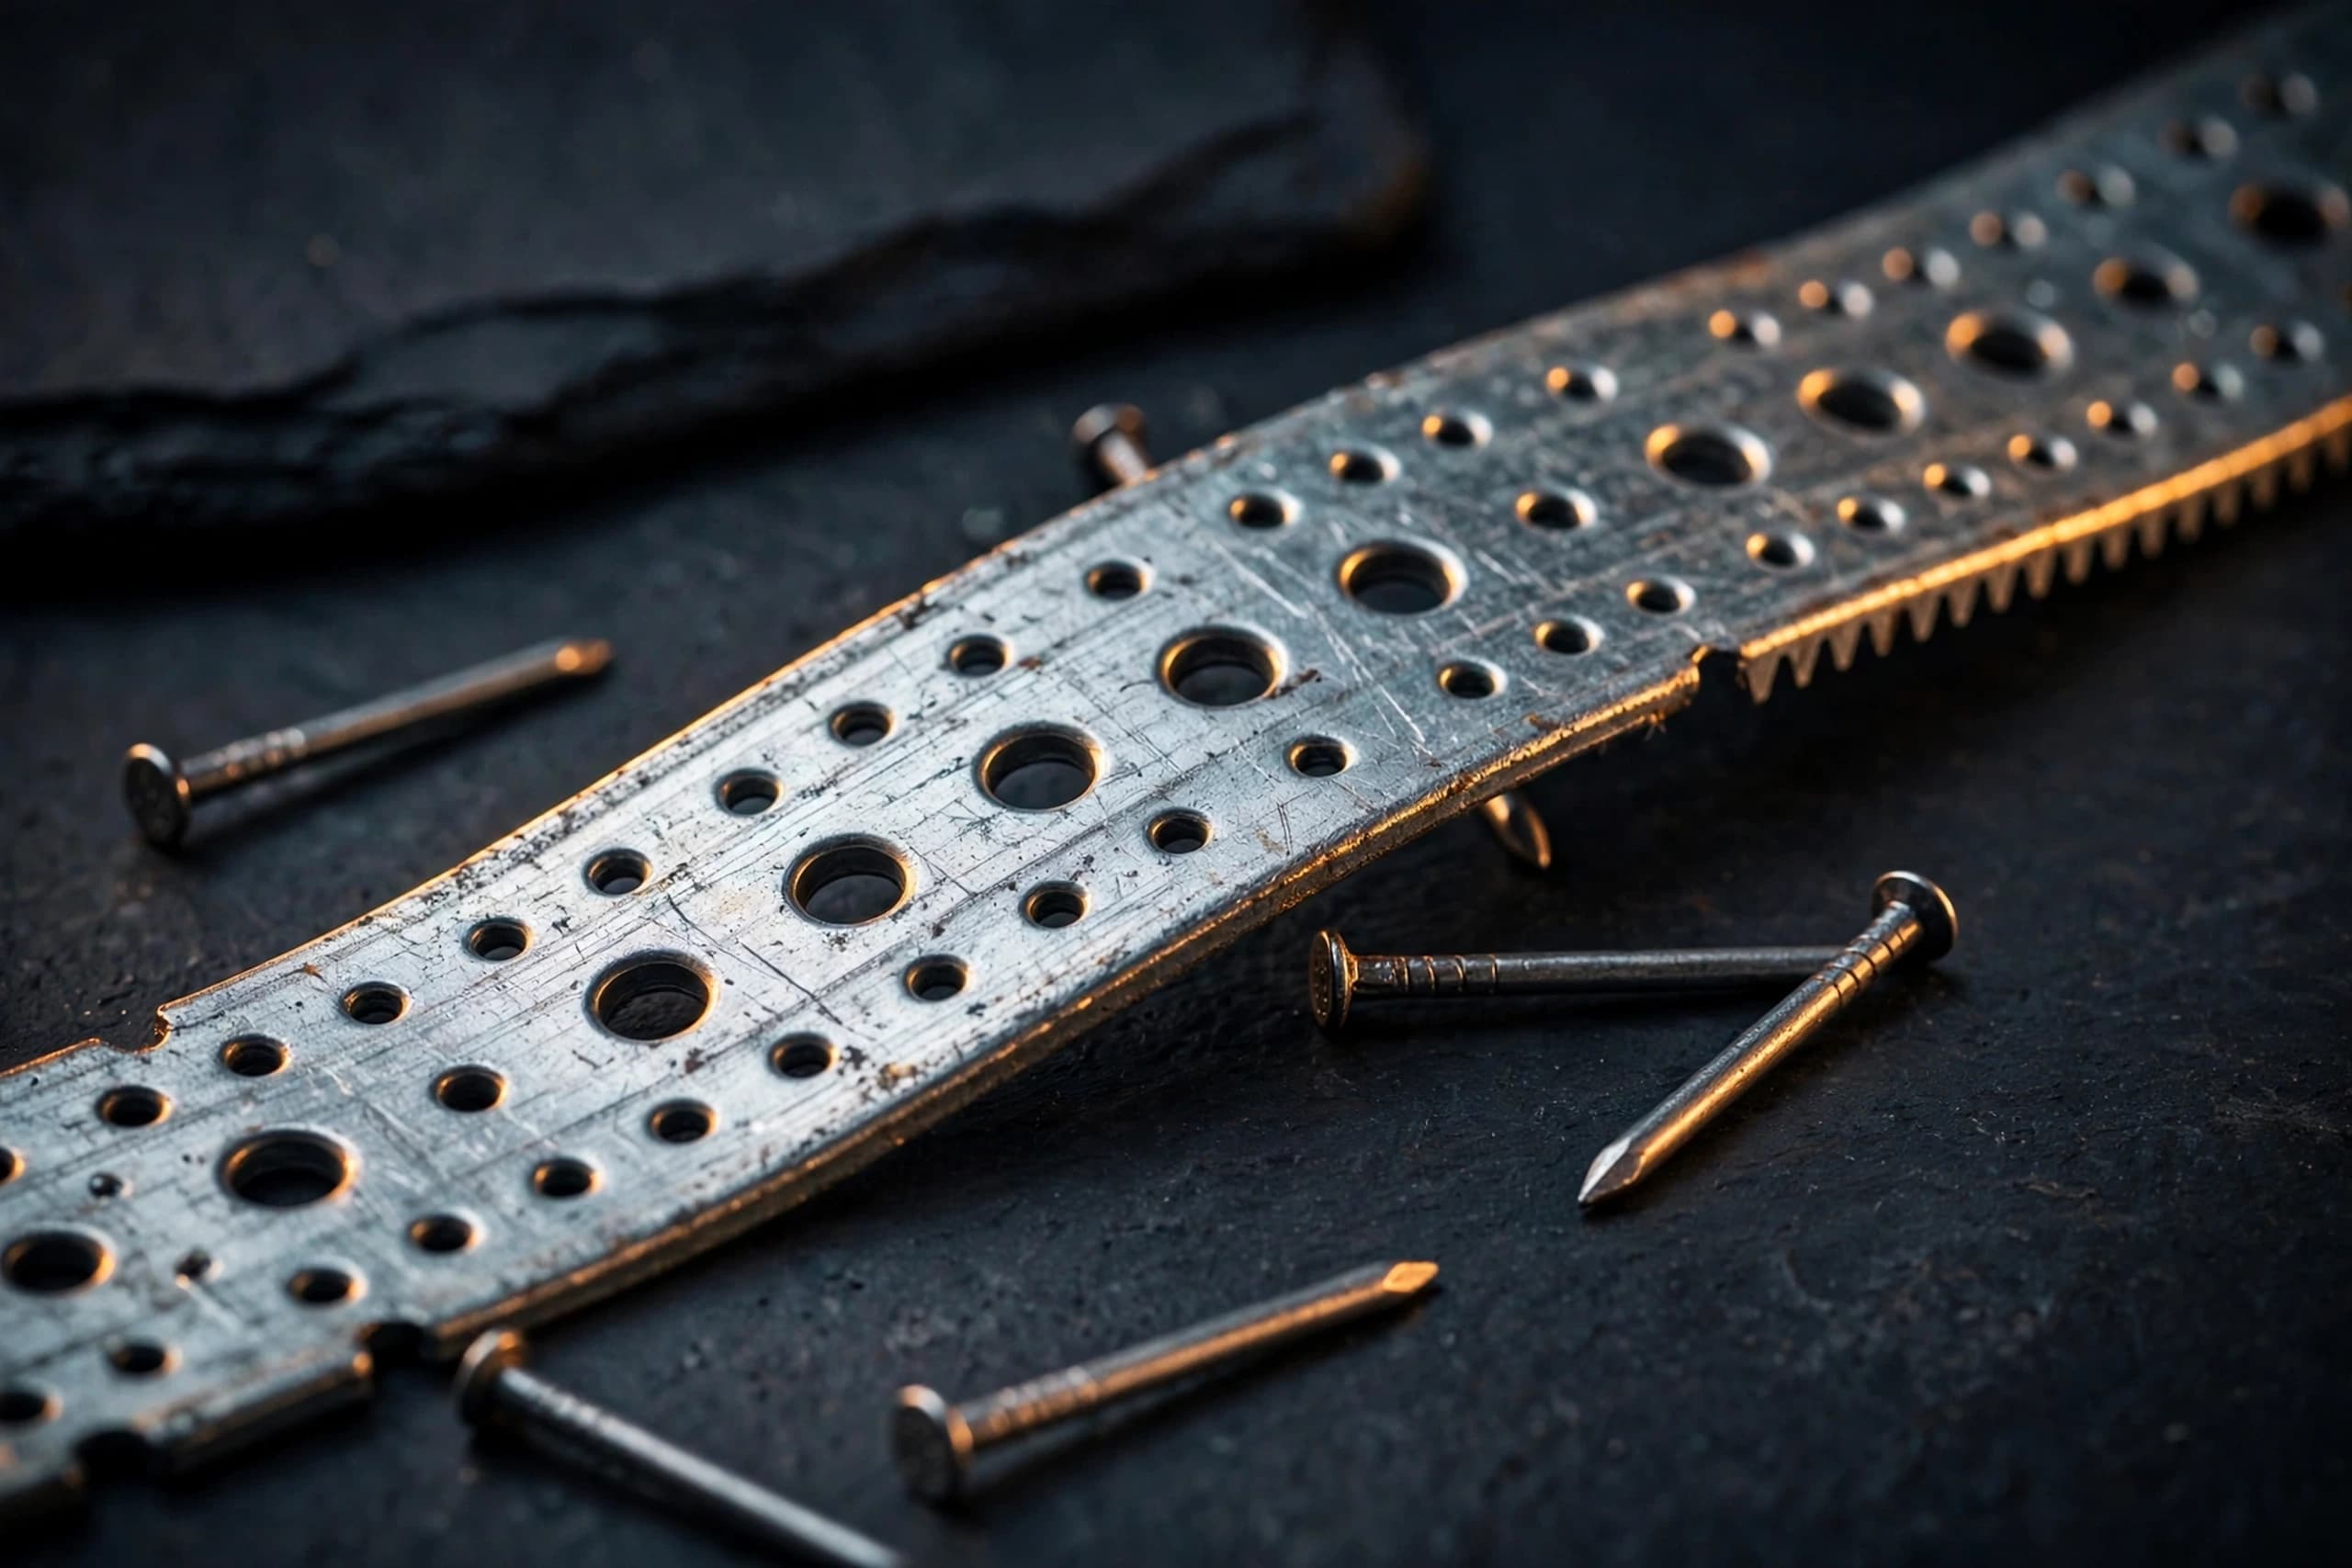
AI-generated media. A hurricane strap — the steel behind the single highest-ROI feature on most pre-2002 homes.
The sample dossier · interactive
Run a home through the model. See the dossier.
This preview runs the same pipeline as the paid dossier — on a transparent toy methodology, with illustrative figures — so you can judge the report craft before you pay.
Pricing · one-time, not a subscription
Find $1,000 a year. Pay $99 once.
Wind-mitigation features cut the windstorm portion of a Florida premium 25–45% when documented — worth $400–$3,600 a year in published savings bands. The dossier shows you which of those dollars are yours.
Illustrative estimate. Modeled from public OIR-B1-1802 discount tables × public home attributes — not a carrier quote. Not insurance advice — confirm with your licensed agent.
Essential
$99
one-time · one address
The core storm-resilience + insurance-savings dossier for one address.
- Full 6-section dossier — PDF + web view
- Storm profile with methodology-labeled Resilience Score
- 7-feature wind-mitigation scorecard
- The Money Page — illustrative savings, broken down per feature
- Hardening roadmap with payback math
- Delivered in under two minutes
Plus
$149
one-time · one address
Everything in Essential, plus the agent handoff and the state's money.
- Everything in Essential
- Prioritized hardening roadmap — highest-ROI move first
- Grant-eligibility check: My Safe Florida Home (up to $10,000)
- The Agent Packet — one page to hand your insurer
- Annual re-score reminder
Partner Pack
$349
one-time · 5 credits
Five report credits, co-branded — built for the people who sell homes.
- 5 report credits — any Florida address
- Co-branded cover with your logo (realtor / agency / roofer)
- Priority generation
- Made for realtors, insurance agents, and roofers
Checkout is one-time via Stripe on your own secure page. Stormbill is a service of HDC Brands LLC. Stormbill provides educational analytics and is not a licensed insurance agency, agent, broker, or adjuster.
Straight answers
Asked at every kitchen table in Florida.
No. A licensed inspection puts an inspector on your roof and produces the OIR-B1-1802 form your carrier files. Stormbill is the analytical layer around that world: we model which of the seven features your home likely has or lacks, what the gap is worth in illustrative dollars, which upgrades pay back first, and whether the My Safe Florida Home program can fund them. Many customers use the dossier to decide whether an inspection — or which upgrade — is worth doing first.